Improve or Move?
Why Improving Your Existing Home Could Be Worth Considering
For many homeowners, there comes a point when the current property no longer feels quite right. Perhaps the kitchen is too small, there is not enough living space, working from home has changed how rooms are used, or the house simply needs updating.
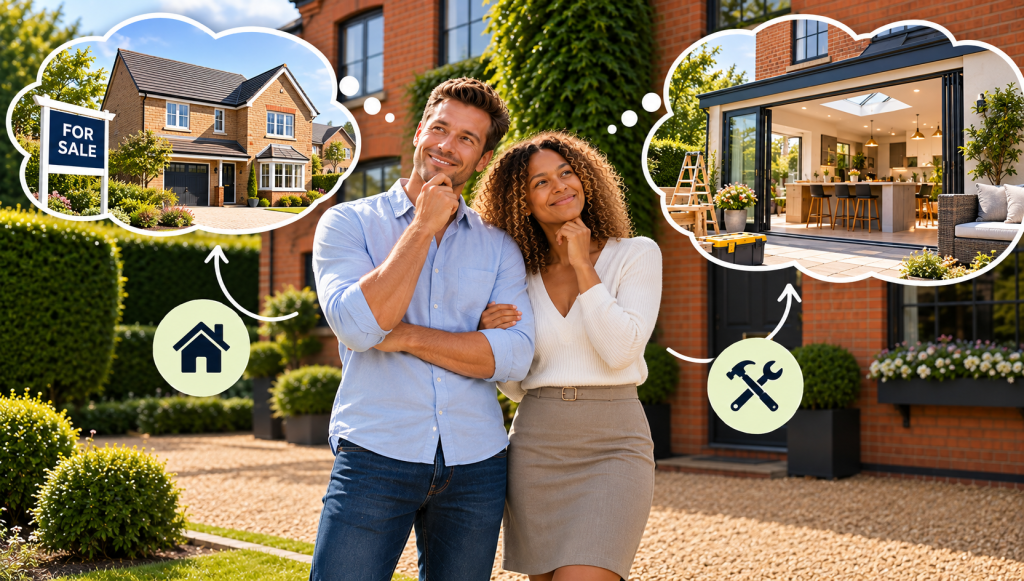
One solution can be to look for another property. However, moving is not the only option. Depending on your circumstances, improving your existing home could provide the space and functionality you need without the disruption of moving.
That does not mean renovating is always the better financial choice. The right option depends on your circumstances, the property, the proposed improvements and the options available to you on how you could fund the work. However, it is worth considering both sides before making a decision.
1. You may be able to stay in an area you already know and enjoyOne of the biggest advantages of improving your existing home is that you don't necessarily have to compromise on location.
You may already have established links with local schools, work, family and friends. You may also value your commute, access to public transport and local amenities
Finding a larger or more suitable property in the same area may mean paying considerably more, assuming one is available at all.
Improving your current property could allow you to change the house while keeping the location.
2. You can design the space around your needs
Moving house means finding a property that already exists. Even if you find something with an extra bedroom, larger kitchen or additional living space, it may still require work to make it suitable for you.
Extending or re-modelling your existing home can give you greater control over how the space is used.
Depending on planning requirements and the structure of the property, improvements could include:
- A rear or side extension
- A loft conversion
- An additional bedroom or home office
- An open-plan kitchen and living area
- An extra bathroom or shower room
- Improved storage
- Better insulation and energy efficiency
- Accessibility improvements
- A new kitchen or bathroom
Planning permission or building regulations approval may be required for some projects, so it is important to establish what permissions and professional input are needed before work begins.
3. Moving comes with its own costs
Buying another property involves more than simply finding the difference between the value of your current home and the price of your next one.
Depending on your circumstances, you may have costs associated with estate agency, conveyancing, surveys, removals, mortgage arrangements and taxation.
For example, Stamp Duty Land Tax (SDLT) applies to qualifying property purchases in England and Northern Ireland, while Scotland and Wales have their own property transaction taxes. The amount payable depends on the circumstances of the purchase.
There may also be mortgage-related costs, including an early repayment charge if you leave an existing mortgage before the end of a relevant deal period.
These costs don't necessarily make moving the wrong choice, but they are part of the overall comparison.
When considering whether to improve or move, it can therefore be useful to compare the total cost of moving with the estimated cost of achieving similar improvements at your current property.
4. Improving your home's energy efficiency could have longer-term benefits
Home improvements aren't necessarily just about appearance.
Insulation, glazing, heating systems and other energy-efficiency measures can potentially improve the performance of a property and may make it more comfortable to live in.
The latest English Housing Survey found that the proportion of homes in Energy Performance Certificate (EPC) bands A to C increased from 23% to 52% over the previous decade. The same survey estimated that the average cost of improving a dwelling to at least EPC band C was £7,320 across all tenures, although the actual cost varies considerably between properties.
Energy improvements should not, however, be viewed as a guaranteed way of increasing a property's value. The suitability, cost and potential benefit of any work will depend on the individual property and the local market.
5. You may be able to improve without taking on a completely new mortgage
Depending on your circumstances, there may be several ways of funding home improvements.
Some homeowners use savings to fund work, while others consider borrowing.
For example, we might be able to apply to your existing mortgage lender for a further advance. This is additional borrowing from the current mortgage lender and may be considered for purposes such as home improvements.
Another possibility could be remortgaging to a different lender and increasing the amount borrowed, although this may involve costs such as product or arrangement fees and potentially an early repayment charge on the existing mortgage.
There are also unsecured borrowing options, depending on the amount required and the individual's circumstances.
The most appropriate option will depend on affordability, the amount required, the term of borrowing, existing mortgage arrangements and the lender's criteria.
6. Remember that borrowing for improvements is still borrowing
It's important not to view additional mortgage borrowing as simply a way of paying for an extension or new kitchen.
A mortgage is secured against your property. Increasing the amount you borrow can increase your monthly payments and the total amount you repay over the life of the borrowing.
Mortgage lenders will also assess affordability. FCA rules require lenders to assess whether a mortgage is affordable, taking relevant income and expenditure into account and considering the impact of future interest-rate increases.
For that reason, homeowners should consider the full cost of a proposed project and the associated borrowing rather than focusing solely on the amount they could potentially borrow.
7. Don't assume every improvement will increase your property's value
It can be tempting to think that spending £30,000 on a home automatically makes it worth £30,000 more.
There is no guarantee that this will happen.
The value added by an improvement can depend on the location, size and condition of the property, the quality of the work and what buyers in the local market are looking for.
An extension that makes a property significantly more functional could be attractive to future buyers, but an expensive specification may not necessarily produce an equivalent increase in market value.
It is therefore sensible to consider improvements primarily in terms of how they will improve your home and your quality of life, rather than assuming they will produce a particular financial return.
8. Staying put can also mean less disruption
Moving home can be a significant undertaking.
There is the process of finding a property, arranging viewings, making an offer, arranging finance, instructing solicitors, completing the legal work and coordinating the move.
Renovation has its own disruption, of course. Major building work can involve noise, dust, temporary loss of rooms and unexpected costs.
However, if the changes required are relatively straightforward, improving your current home may allow you to solve the specific problem without changing your address.
So, should you improve or move?
For some homeowners, moving may provide the most practical solution. For others, improving the property they already own could provide the additional space or functionality they need while allowing them to remain in an area they like.
A useful starting point is to compare the two options realistically:
If you move:
- What would the next property cost?
- What transaction and moving costs would apply?
- What would your new mortgage payments look like?
- Would you need to compromise on location or property type?
- Would the new property require work anyway?
If you improve:
- What work is actually required?
- What will the project cost, including a contingency for unexpected expenses?
- Will planning permission or building regulations approval be needed?
- How would you fund the work?
- What would additional borrowing cost over its full term?
- Can you comfortably afford the repayments if circumstances or interest rates change?
- Would the improvements make the property more suitable for your longer-term needs?
Taking time to compare the numbers can help you make a more informed decision.
How a mortgage adviser can help
If you're considering borrowing to fund home improvements, We can discuss the mortgage options that may be available to you based on your individual circumstances.
This might include considering whether additional borrowing from your existing lender, remortgaging or another form of finance could be appropriate. Any recommendation should take account of your circumstances, affordability and requirements.
Your home may be repossessed if you do not keep up repayments on your mortgage.
This article is for general information only and does not constitute personal financial advice. Mortgage and property decisions depend on individual circumstances and lending criteria. Tax rules, rates and allowances can change, and the tax treatment of property transactions depends on individual circumstances. Before making a decision, consider obtaining appropriate professional advice.